
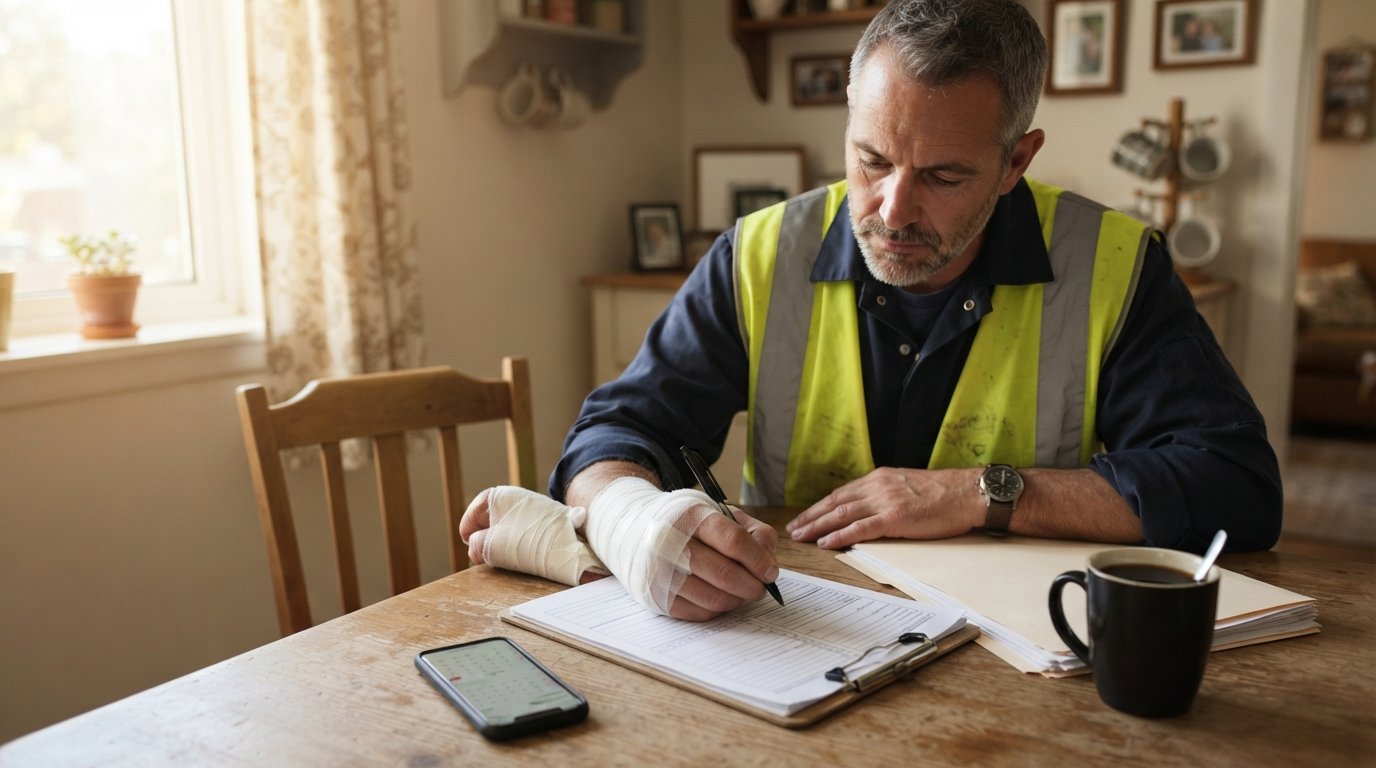
Workers Compensation Claim Process for Injured Employees
Understand each step of the workers compensation claim process for injured employees. Call (833)-248-4565 for guidance on your claim.
By Camila Reyes
Every year, millions of American workers are injured on the job, and many face a confusing maze of paperwork, deadlines, and insurance company tactics just to get the medical care and wage replacement they deserve. If you were hurt at work, you have rights, but those rights depend on following a specific legal procedure that begins the moment you report your injury. Understanding the workers compensation claim process for injured employees is the first step toward protecting your health, your income, and your legal options. This guide breaks down each stage of the process in plain language, from notifying your employer to disputing a denied claim, so you can move forward with confidence.
Reporting Your Injury and Notifying Your Employer
The workers compensation claim process for injured employees officially starts with notice. In nearly every state, you must tell your employer about your workplace injury within a strict deadline, often as short as 30 days from the date of the accident or from the date you realized the injury was work related. Failing to report promptly can jeopardize your entire claim, even if your injury is serious and clearly caused by your job. Do not assume your supervisor saw it happen or that a verbal comment is enough. Follow your company policy for written notice, and keep a copy for your records. In a text or email, state the date, time, location, and a brief description of what happened and what body parts were hurt. Avoid guessing at medical diagnoses or speculating about fault. Just stick to the facts.
Once you notify your employer, most states require them to report the injury to their workers compensation insurance carrier within a set number of days, often 7 to 10. Your employer should also provide you with a list of approved doctors or a claim form. If they do not, ask for it in writing. This early documentation matters because the insurer will scrutinize the timeline later. A prompt, written report creates a record that you took the injury seriously and followed the rules, which makes it much harder for an insurer to argue that your injury was not work related or that you waited too long.
Seeking Medical Treatment and Understanding the Doctor's Role
Getting the right medical care is both a health priority and a legal one. In many states, you must see a doctor from your employer's approved list, at least for the first visit. If you go to your own physician without authorization, the insurer may refuse to pay those bills. When you see the doctor, be honest and specific about your symptoms and how they developed. Tell the doctor that the injury happened at work and describe your job duties that contributed to it. The medical report generated from this visit becomes a cornerstone of your claim, so make sure it accurately reflects the mechanism of injury and your limitations.
Follow your doctor's treatment plan and restrictions without exaggeration or omission. If you are given light duty restrictions, provide them to your employer in writing and ask whether modified work is available. If your employer cannot accommodate those restrictions, you may be entitled to temporary disability benefits while you recover. Keep a personal file with every medical record, work status note, and prescription receipt. Insurers often dispute claims by pointing to gaps in treatment or inconsistent reports, so a well organized medical history strengthens your position. If you feel rushed or dismissed by a company chosen doctor, you may have the right to request a change of physician under your state's rules, but you must follow the proper procedure rather than simply switching on your own.
The Role of the Employer's Insurer and Independent Medical Exams
Once your claim is filed, the employer's workers compensation insurer takes over the investigation. An adjuster will contact you, request records, and may ask for a recorded statement. You are generally required to cooperate with reasonable requests, but you should be careful. You do not have to guess about future medical needs or speculate about how the injury happened. Answer factual questions truthfully and keep a copy of any statement you give. The adjuster may also schedule an independent medical exam, often called an IME. Despite the name, the doctor is not independent in the sense of being neutral; they are paid by the insurer. That does not mean you should refuse to attend, because refusing an IME can result in suspension of your benefits. Instead, prepare for it the same way you would for any important medical appointment: bring your records, describe your symptoms consistently, and do not exaggerate or minimize.
After the IME, the insurer may accept your claim, deny it, or accept it only in part. You should receive a written decision. If the insurer accepts the claim, you are entitled to reasonable and necessary medical treatment and, depending on your state, wage replacement benefits. If the insurer denies the claim or disputes the severity of your injury, do not panic. A denial is not the final word. You have appeal rights, and the workers compensation claim process for injured employees includes a formal dispute resolution system designed to resolve exactly these disagreements. The key is to act quickly and to understand the deadlines for filing an appeal, which are often short, sometimes as little as 30 to 60 days from the date of the denial notice.
Disputing a Denied or Underpaid Claim
If your claim is denied or you believe your benefits are too low, you can challenge the decision. The first step is usually to request a review or reconsideration with the insurer, providing additional medical evidence or a detailed explanation of why the denial is wrong. If that fails, you can file a formal appeal with your state's workers compensation board or commission. Many states offer a mediation or informal conference before a full hearing. At a hearing, you present evidence and testimony before an administrative law judge or commissioner. You have the right to be represented by an attorney at these proceedings, and in many cases, attorney fees are paid from the award or settlement rather than out of your pocket upfront. Having a lawyer can make a significant difference in complex disputes, especially when the insurer has hired its own medical experts and legal counsel.
Common reasons for denial include disputes about whether the injury happened at work, whether you missed a reporting deadline, whether your medical treatment was authorized, or whether you were actually an employee rather than an independent contractor. Each of these issues can be challenged with the right evidence. For example, if the insurer claims your injury was pre existing, your doctor can explain how the work accident aggravated or accelerated the condition. If the insurer claims you were not an employee, payroll records, text messages, and witness statements can establish the true working relationship. Do not simply accept a denial because it sounds official. The appeal process exists precisely because insurers sometimes get it wrong or pressure injured workers to give up.
How Workers Compensation Relates to a Third Party Injury Claim
Workers compensation is generally the exclusive remedy against your employer for a work related injury, meaning you cannot sue your employer in most cases. However, if a third party caused or contributed to your injury, you may have a separate personal injury claim against that third party. Examples include a defective piece of equipment manufactured by another company, a careless driver who hit you while you were working on a road crew, or a property owner who failed to maintain a safe premises. In these situations, you may be able to pursue both workers compensation benefits and a third party claim, but the two are not entirely independent. The insurer may have a lien on your third party recovery to recoup benefits it paid, and the rules for coordinating the two claims vary by state. An experienced personal injury attorney can help you understand how to protect your rights in both processes.
It is also important to recognize that the workers compensation claim process for injured employees is not designed to compensate for pain and suffering. Workers compensation typically covers medical expenses, a portion of lost wages, and sometimes permanent disability benefits. A third party claim, on the other hand, can include damages for pain, suffering, and emotional distress. That is why identifying all potential responsible parties early is critical. If you are unsure whether a third party was involved, consult with a lawyer who handles both workers compensation and personal injury cases. For families facing the most tragic outcome, understanding the wrongful death claim process after a fatal accident can provide clarity on the separate legal path that may be available when a workplace injury results in death.
Practical Steps and Timeline for Injured Employees
To keep your claim on track, follow a clear sequence. The exact deadlines vary by state, but the general framework below applies in most jurisdictions. Think of this as your checklist for the first several weeks after an injury.
- Report the injury immediately: Tell your supervisor and complete any written incident report the same day, keeping a copy for yourself.
- Get authorized medical care: See a doctor from the approved list, describe the work related cause, and follow all treatment recommendations.
- File the claim form: Submit the employee portion of the claim form to your employer or the state workers compensation office within the deadline.
- Document everything: Keep records of medical visits, work restrictions, lost wages, and all communications with the insurer and employer.
- Respond to the insurer but stay cautious: Cooperate with reasonable requests, attend any required IME, and avoid signing documents you do not understand.
After the initial filing, the insurer has a set period to accept or deny the claim. If you receive a denial, note the appeal deadline immediately and consider consulting an attorney. Throughout the process, continue medical treatment as prescribed and keep your employer informed of your availability for modified duty. If your condition changes or you are released to full duty but still have restrictions, update your claim file. A well documented, consistently followed claim is harder to dispute and more likely to result in timely benefits.
When to Seek Legal Help
You are not required to hire a lawyer for every workers compensation claim. Many straightforward claims are resolved without legal representation. However, certain situations call for professional guidance. If your claim is denied, if the insurer is delaying authorization for necessary treatment, if you are pressured to return to work before you are ready, if you are offered a settlement that seems low, or if you suspect a third party is responsible, speaking with an attorney is a smart move. A lawyer can explain your rights under your state's specific rules, help you gather evidence, and represent you at hearings. For readers who want to explore their options, platforms like AttorneyDirectory.Lawyer allow you to search for attorneys in your area and request a quote with no obligation to hire. This can be a useful starting point when you are deciding whether to handle a claim on your own or bring in professional help.
Keep in mind that workers compensation laws are state specific, and deadlines are strict. What works in one state may not work in another. The information in this article is educational and not legal advice. If you are navigating a complex claim or a denial, consider consulting a licensed workers compensation attorney in your state to protect your rights and maximize your chances of a fair outcome.
The workers compensation claim process for injured employees can feel overwhelming, especially when you are in pain and worried about lost income. But by reporting promptly, seeking authorized medical care, documenting every step, and knowing when to push back against a denial, you can take control of your claim. Start with the basics, stay organized, and do not be afraid to ask for help when the stakes are high.