
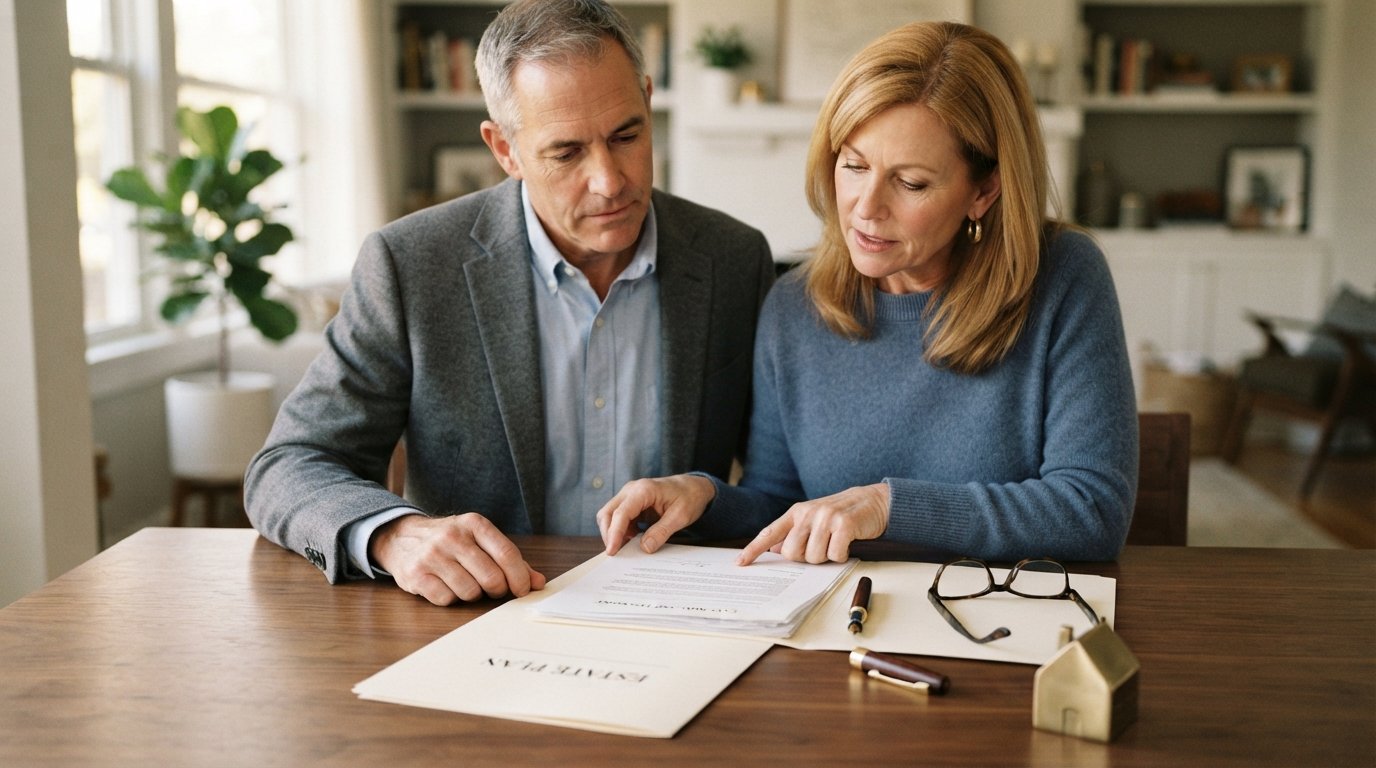
When to Update Your Will and Estate Plan: Key Life Triggers
Certain life events should trigger a review of your estate documents. Knowing when to update your will and estate plan can spare your family probate court.
By Brooke Callahan
A will is not a document you sign once and forget. It is a living piece of your financial and personal life, and it needs to grow and change as you do. Yet study after study shows that a majority of American adults either do not have a will at all or are working from one they signed years, sometimes decades, ago. The result is that families end up in probate court, assets go to the wrong people, and the intentions of a deceased loved one get second-guessed by strangers. Knowing when to update your will and estate plan is just as important as creating one in the first place.
This guide walks through the specific life events that should trigger a review of your estate planning documents. It also explains how often to revisit your plan even when nothing dramatic has happened, and how to take the first step toward professional help when you are ready. The information here is educational only. It is not legal advice, and no article can replace a conversation with a licensed attorney in your state.
Why an Outdated Will Is Worse Than No Will at All
Many people assume that an old will still protects their family because it reflects their wishes at some point in the past. In reality, an outdated will can create more confusion than having no will at all. Imagine a parent who named a now-estranged sibling as executor in 2012, or a person who left a house to a former partner before a divorce. When that document surfaces after death, the family must either honor terms that no longer reflect reality or fight them in court. Both outcomes cost time, money, and relationships.
An outdated estate plan also fails to account for changes in tax law, state probate rules, and the way your assets are titled. A will that made perfect sense ten years ago may now route assets through a lengthy probate process that could have been avoided with a simple trust update. In some states, the failure to update beneficiary designations on retirement accounts means the wrong person inherits money regardless of what the will says.
There is also the human side. Family dynamics shift. Children become adults. A once-trusted friend may no longer be the right person to make medical decisions for you. When you do not update your will and estate plan, you leave those decisions to a default process defined by state law rather than by your own voice. That default process rarely matches what you would want.
The Life Events That Should Trigger an Estate Plan Review
Legal professionals generally recommend that you review your estate plan every three to five years even if nothing has changed. But certain life events should push you to update your will and estate plan much sooner. If any of the following situations apply to you, it is time to schedule a review with an estate attorney.
- Marriage or remarriage: A new spouse changes your legal rights to inherit, and your old will may leave them with nothing.
- Divorce or separation: Many states automatically revoke gifts to a former spouse, but not all, and beneficiary designations often survive the divorce.
- Birth or adoption of a child: You may need to name a guardian, create a trust, and adjust how assets are distributed.
- Death of a beneficiary, executor, or trustee: If the person you named can no longer serve, the court may appoint someone you never chose.
- Significant change in assets: A new home, business, inheritance, or large investment can shift your estate into a different planning category.
Each of these events changes the assumptions your plan was built on. Marriage, for example, does not automatically override a will in every state. In some jurisdictions, a spouse may have an elective share right, but the practical result is often litigation that drains the estate. Updating your will to reflect the new marriage is far simpler than letting a court decide.
The birth of a child is another classic trigger. Without a named guardian, a judge chooses who raises your children if both parents die. That person may be a relative you would never have selected. A simple update to your will and estate plan can prevent that outcome. The same logic applies when a child becomes an adult, because the default rules for minors no longer apply and your child may now inherit outright rather than through a trust.
Financial and Legal Changes That Require an Update
Life events are not the only triggers. The financial and legal landscape around you changes constantly, and your estate plan needs to keep pace. Tax law is a moving target. Federal estate tax exemptions have shifted dramatically over the past two decades, and state-level estate and inheritance taxes vary widely. A plan that was tax-efficient in 2016 may now create an unnecessary tax bill or miss a planning opportunity that did not exist before.
State law changes matter too. If you move to a new state, your will may not be valid, or it may be valid but interpreted differently than you expect. Community property states treat assets differently than common law states. Homestead exemptions and probate procedures vary from one jurisdiction to the next. When you cross state lines, you should update your will and estate plan to match your new legal home.
Changes in asset ownership also deserve attention. If you have retitled property, opened new accounts, or transferred assets into a trust, your will may no longer control those assets. Beneficiary designations on life insurance policies and retirement accounts override what your will says. If you have not reviewed those forms since you opened the accounts, you may be sending money to an ex-spouse or a deceased relative.
Business owners face an additional layer of complexity. A business interest is often the largest asset in an estate, and it requires specialized planning. Without a buy-sell agreement, succession plan, or trust structure, a business can be forced into liquidation to pay estate taxes. If you own a company, update your will and estate plan whenever the business changes hands, gains new partners, or increases in value. You may also want to consult an attorney who focuses on corporate matters; you can find lawyers in your city and request a quote through AttorneyDirectory.Lawyer, a directory that connects people with participating attorneys. There is no obligation to hire, and the site is not a law firm or a lawyer referral service.
How Often Should You Review Your Estate Plan?
Even if none of the major life events above apply, you should still review your estate plan on a regular schedule. A common recommendation is every three to five years, but some attorneys suggest an annual check-in for high-net-worth families or those with complex trust structures. The goal is not to rewrite the entire plan each time. It is to confirm that the people you named are still the right people, that the assets listed are still accurate, and that the law has not shifted in a way that undermines your intentions.
A practical approach is to tie your review to a recurring event, like filing your taxes or renewing your homeowner's insurance. During that review, ask yourself a few simple questions. Have any of my beneficiaries died or become unable to manage money? Have I acquired or sold any significant assets? Has my relationship with my executor or trustee changed? Have I moved to a new state? If the answer to any of these is yes, it is time to update your will and estate plan.
It also helps to keep a simple inventory of your estate documents and the professionals who helped create them. If you used a lawyer in the past, that office may have a copy of your will and can help you update it. If you used a do-it-yourself service, you should still consider having an attorney review the document before you rely on it. Estate planning is one of the few areas where a small mistake can create years of legal problems for your family.
Special Situations: Blended Families, Special Needs, and Charitable Giving
Some family situations require more frequent updates than others. Blended families are a classic example. If you have children from a previous marriage and a new spouse, your estate plan must balance competing interests. Without careful planning, your children may inherit nothing if your spouse inherits everything and then changes their own will. Updating your will and estate plan after every major family change is essential in this situation.
Families with a special needs child face similar urgency. A direct inheritance can disqualify a child with disabilities from means-tested government benefits. A special needs trust, sometimes called a supplemental needs trust, can protect those benefits while still providing for your child. But the trust must be drafted correctly, and it must be funded properly. If you already have a trust in place, you should review it whenever the beneficiary's circumstances change or when the law governing benefits shifts.
Charitable giving is another area where plans need periodic attention. If you have named a charity in your will, confirm that the organization still exists and still aligns with your values. If you have created a donor-advised fund or private foundation, review the succession plan for who will manage it after your death. For readers who want a deeper understanding of how different trust structures work, our guide on types of trusts explained for estate planning walks through the most common options and when each one makes sense.
What Happens If You Do Not Update Your Plan
Failing to update your will and estate plan does not mean your wishes disappear. It means they are interpreted through a document that no longer reflects your life. The consequences can be severe. Assets may go to people you no longer know or trust. A former spouse may inherit your retirement account because you never changed the beneficiary form. Your children may end up in the care of someone you would not have chosen. And your family may spend months or years in probate court sorting out the mess.
Probate is the legal process of validating a will and distributing assets under court supervision. It is public, it is slow, and it is expensive. A well-maintained estate plan can often avoid probate entirely through the use of trusts, joint ownership, and beneficiary designations. But those tools only work if they are current. An outdated plan may push your estate into probate even though you thought you had avoided it.
There is also an emotional cost. Families who feel that a loved one's wishes were ignored or misunderstood often carry resentment for years. Updating your will and estate plan is not just a legal task. It is an act of care for the people you leave behind. It gives them clarity, reduces conflict, and lets them focus on grieving and healing rather than fighting in court.
Steps to Take When You Decide to Update Your Plan
Once you recognize that it is time to update your will and estate plan, the process is straightforward if you approach it in order. Start by gathering your existing documents: your will, any trusts, powers of attorney, healthcare directives, and a list of beneficiary designations. Then make a list of what has changed since the documents were signed. That list becomes the agenda for your meeting with an attorney.
Next, decide who you want to serve in key roles. Your executor handles the probate process. Your trustee manages trust assets. Your agent under a power of attorney makes financial decisions if you become incapacitated. Your healthcare proxy makes medical decisions. These roles should go to people you trust and who are willing and able to serve. It is a good idea to name backups in case your first choice cannot act.
Finally, work with a licensed attorney in your state to draft the updated documents and sign them properly. Estate planning has strict formalities. A will signed without the required witnesses may be invalid. A trust that is not funded may have no effect. An attorney can make sure your plan complies with state law and actually does what you intend. If you do not already have an attorney, you can use a directory service to find one in your area and request a quote with no obligation to hire.
Planning ahead is one of the most responsible things you can do for your family. The law does not require you to update your will and estate plan on a specific schedule, but your life does. Every marriage, birth, death, move, and major financial change is a signal to revisit the documents that speak for you when you cannot. Treat those signals seriously, and your family will be grateful for the clarity you leave behind.