
What Happens During Probate After a Loved One Dies
Probate after a loved one dies follows steps from filing the will to paying debts. Call 8332484565 to find estate lawyers and request a quote.
By Luis Navarro
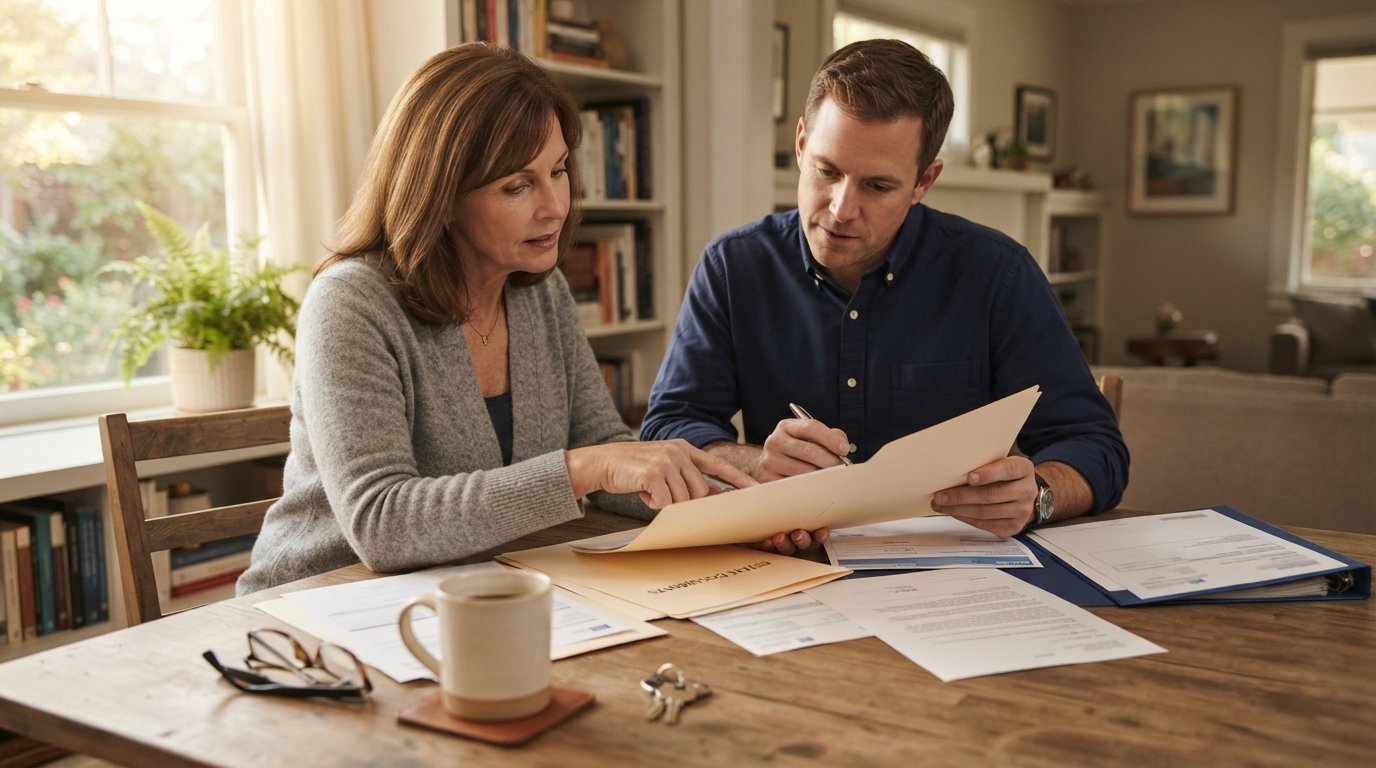
The phone call comes, and then the tasks begin. Funeral arrangements, family notifications, and somewhere in the middle of the grief, a folder of documents lands on your kitchen table. Bills need paying. A house sits empty. A bank account is frozen. You keep hearing the same word from well-meaning relatives: probate. Understanding what happens during probate after a loved one dies will not erase the sadness, but it can replace some of the confusion with a clear sequence of events, realistic timelines, and a sense of what you actually control.
Probate is the court-supervised process of settling a deceased person's estate. It confirms whether a will is valid, identifies and values what the person owned, pays outstanding debts and taxes, and distributes whatever remains to the rightful heirs or beneficiaries. Most estates in the United States go through some form of probate, though the scope varies dramatically. A small estate with a surviving spouse and a clear will might wrap up in a few months with minimal court involvement. A larger estate with disputes, business interests, or property in multiple states can take years.
This guide walks through the probate timeline step by step, explains who does what, and highlights the moments where families most often get stuck. It is general information, not legal advice, and every state has its own rules and forms. If your situation involves conflict, debt, or significant assets, an estate attorney can clarify your options. A directory such as AttorneyDirectory.Lawyer can help you find estate and trust lawyers in your city and request a quote, with no obligation to hire, which is often the fastest way to get a straight answer about your specific case.
The First Steps: What Must Happen Before Probate Begins
Before any court is involved, someone has to handle the immediate realities of a death. The law does not wait for the probate process to start, and certain obligations land on whoever is closest to the deceased. This early period shapes how smoothly the formal estate administration will go later.
The first priority is securing property. If the person died at home, the house should be locked, valuables inventoried, and pets cared for. Vehicles should be moved off the street and insured. Mail should be collected so that bills, bank statements, and tax notices do not pile up unread. If the deceased owned a business, someone needs to keep basic operations running or at least protect the assets until a personal representative is appointed.
Next comes locating the will. The original document matters more than a copy. It may be in a filing cabinet, a safe deposit box, a law office, or with a family member. The person named in the will as executor, sometimes called a personal representative, generally has the first right to serve. If no will exists, state intestacy laws determine who inherits and who gets priority to administer the estate.
Within a few weeks, several administrative to-dos typically need attention. The order can vary by state and situation, but the core tasks look like this:
- Order certified death certificates. Banks, insurers, and government agencies will each want one, so order more copies than you think you need.
- Notify Social Security and other benefit programs. Payments received after death may need to be returned, and survivor benefits may be available.
- Open a probate case. This usually means filing the will and a petition with the probate court in the county where the deceased lived.
- Notify creditors and beneficiaries. Many states require a formal notice published in a newspaper and mailed to known creditors.
One practical tip: start a single master file, either paper or digital, with every account number, contact, and document. Probate involves repeating the same information to banks, courts, and agencies, and a well-organized file saves hours. If the estate is complex or family members disagree about who should serve as executor, this is the moment to consult an attorney rather than after deadlines have passed.
Opening the Estate: The Court Appointment Process
Formal probate begins when a petition is filed with the court. The petition identifies the deceased, lists the known heirs and beneficiaries, states whether a will exists, and asks the court to appoint a personal representative. In many states, this filing must happen within a set window after death, sometimes 30 to 90 days, though late filings are often allowed with explanation.
The court then reviews the paperwork and, if everything is in order, issues formal authority. This document goes by different names depending on the state: letters testamentary when there is a will, letters of administration when there is not, or a certificate of appointment. Until that document exists, banks and title companies generally will not speak with the executor, and the estate cannot legally take major actions. This is one of the most common sources of frustration for families, because it can take several weeks to a few months to obtain.
Once appointed, the personal representative takes on a fiduciary role. That means a legal duty to act in the best interests of the estate and its beneficiaries, not in the representative's own interest. Fiduciary duties include keeping estate money separate from personal money, keeping records, avoiding conflicts of interest, and distributing assets only as the will or law directs. Breaching those duties can lead to personal liability, which is why even capable family members sometimes hire professionals to assist.
Notice requirements come next. Known creditors and beneficiaries typically receive written notice by mail, and most states also require a published notice in a local newspaper to reach unknown creditors. Creditors then have a limited window, often four to six months, to file claims against the estate. Debts that are not properly presented within that window may be barred, which is one reason the timeline matters so much.
Inventory, Valuation, and the Paper Trail
With authority in hand, the personal representative must identify everything the deceased owned and determine what it was worth as of the date of death. This inventory is filed with the court in many states and forms the basis for creditor payment, tax filings, and eventual distribution.
Not everything counts as a probate asset. Assets that pass outside probate, sometimes called non-probate assets, are excluded. Common examples include life insurance proceeds paid to a named beneficiary, retirement accounts with designated beneficiaries, property held in joint tenancy with right of survivorship, and assets placed in a revocable living trust. Understanding this distinction often surprises families, because a person can have a large net worth and still have a small probate estate, or the reverse.
Valuation is more than adding up bank balances. Real estate needs a date-of-death appraisal. Vehicles, jewelry, art, and household contents may need professional valuation. Business interests can require a formal business appraisal. Closely held stock, partnership interests, and intellectual property add another layer of complexity. The personal representative should document how each value was determined, because tax authorities and beneficiaries may both ask.
Meanwhile, the estate needs its own financial identity. A bank account in the name of the estate allows the representative to collect income, pay bills, and keep estate money separate from personal funds. An Employer Identification Number from the IRS is usually required. From this point forward, every dollar in and out should be traceable. Courts and beneficiaries can review these records, and sloppy bookkeeping is one of the leading reasons probate disputes escalate.
Paying Debts, Taxes, and Creditors
Before anyone inherits a dollar, valid debts and taxes must be paid. This is the stage where probate becomes a balancing act: the representative must satisfy legitimate claims while protecting the estate from demands that are invalid, duplicated, or barred by the statute of limitations.
Typical debts include mortgages, credit cards, medical bills, utility accounts, personal loans, and outstanding income taxes. Secured debts, such as a car loan or mortgage, generally follow the property. If the estate cannot pay a secured debt, the lender may repossess or foreclose, though family members sometimes have the option to take over payments or refinance. Unsecured debts are paid from estate assets according to state priority rules, which usually place funeral expenses, administration costs, and taxes near the top.
Tax obligations do not end at death. The estate may owe federal estate tax if the total value exceeds the federal exemption threshold, which is high enough that most estates do not pay it, but state estate or inheritance taxes apply in some states at much lower thresholds. The deceased's final income tax return must also be filed, and in some cases the estate itself files income tax returns for income earned after death. Deadlines and elections here are technical, and missed filings can trigger penalties that come out of the beneficiaries' shares.
Creditors do not always play fair. Some debt collectors contact grieving family members and imply that they are personally responsible for a relative's debts. In most cases, children and other heirs are not personally liable for the deceased's debts unless they co-signed, shared the account, or received assets that law requires them to return. If collection pressure feels aggressive or confusing, it is reasonable to pause and get guidance from an estate attorney before paying anything.
Distribution to Beneficiaries and Closing the Estate
Once debts and taxes are resolved, or adequate reserves are set aside, the personal representative can distribute what remains. If a will exists, distributions follow its terms. If not, state intestacy law divides the estate among surviving spouses, children, and other relatives in a fixed order. Specific bequests, such as a piano or a sum of cash, are handled first, and the residue is divided according to the will or statute.
Before final distribution, many states require the representative to file an accounting with the court showing all receipts, disbursements, and proposed distributions. Beneficiaries then have a window to object. If everyone agrees and the estate is small, some states allow a simplified closing with minimal paperwork. If disagreements exist, the court may need to resolve them before anyone receives a final share.
Distributions can take several forms. Cash is straightforward. Real estate may be deeded to heirs, sold and the proceeds split, or transferred to one heir who buys out the others. Retirement accounts and life insurance typically pass directly to named beneficiaries and never enter the probate estate, though they may still affect taxes. For tangible personal property, families often use a rotation or lottery system to divide items fairly, and the representative should document the method used.
After final distributions, the representative files a closing document, and the court formally discharges them from duty. Only then is the probate case truly finished. Even after closing, records should be kept for several years. Tax authorities can audit returns, and beneficiaries occasionally raise questions long after the fact. A complete file protects the representative and gives the family a reliable history of what happened.
How Long Probate Takes and What Can Slow It Down
There is no single answer to how long probate lasts. A simple, uncontested estate might close in six to nine months in some states. A moderate estate with a house, investments, and routine debts often takes a year to eighteen months. Contested estates, multi-state property, business interests, or tax audits can stretch the process to two or three years or more.
Several factors predictably slow things down. Creditor claim periods set a minimum timeline in many states. Real estate sales depend on the market and buyer financing. Disputes among heirs, claims of undue influence, or questions about the will's validity can trigger litigation that pauses everything else. Missing documents, unclear beneficiary designations, and deceased beneficiaries whose own heirs must be located add delay. Estates with assets in more than one state may require a separate ancillary probate in each state, doubling the administrative work.
Speed is not the only goal. Rushing distributions before debts and taxes are settled can leave the representative personally exposed if a creditor surfaces later. A deliberate pace, with proper notices and documentation, usually protects everyone involved. Families who want to reduce friction can take practical steps now: keep beneficiary designations current, consider whether a revocable trust fits their situation, name a reliable executor, and talk openly with heirs about expectations. Estate planning done in advance does not eliminate probate, but it can make the process far shorter and less expensive.
If the estate is small, many states offer simplified procedures. These might include a small estate affidavit, a summary administration, or a transfer of assets by affidavit after a waiting period. The thresholds vary widely, so it is worth checking your state's rules before assuming a full probate case is required. When in doubt, a short consultation with an estate lawyer can clarify which path applies and what forms to file.
The probate process after a loved one dies is administrative, but it happens during one of the hardest seasons of life. Knowing the sequence, from securing the home and filing the will to paying creditors and distributing what remains, turns an overwhelming blur into a series of manageable steps. You do not have to memorize every rule or predict every complication. You do need to keep good records, meet deadlines, and ask for help when the estate is complex or the family is divided. That combination is usually enough to move the estate forward and, eventually, to close the chapter with the paperwork completed and the heirs protected.