
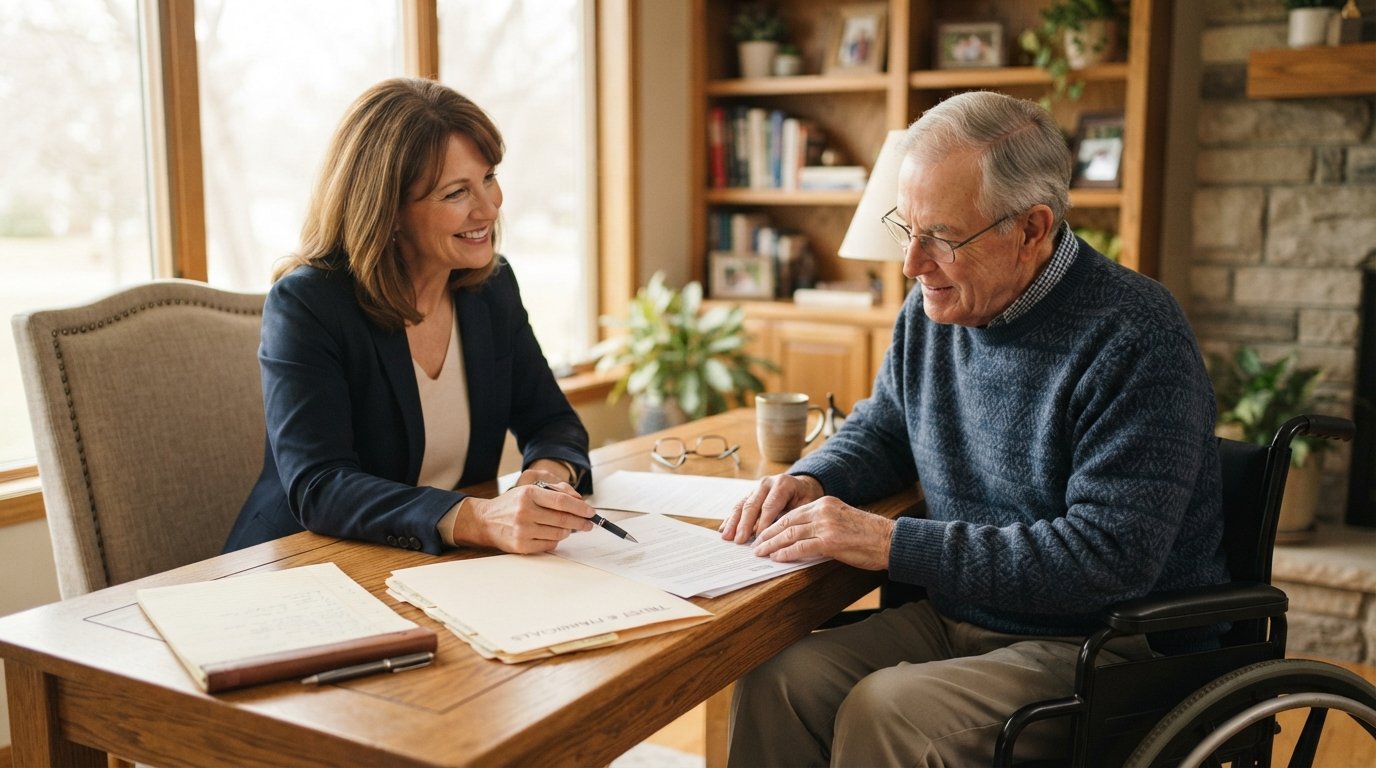
Special Needs Trust Basics: Protect a Beneficiary's Future
Special needs trust basics for protecting a beneficiary: learn how to preserve benefits and provide for a loved one. Call (833)-248-4565 for guidance.
By Grace Griffin
When you have a loved one with a disability, providing for their future without jeopardizing their access to critical government benefits is one of the most important and complex challenges you will face. The task is not just about leaving money behind; it is about structuring that money in a way that enhances their life rather than disqualifying them from the support they depend on. This is where a special needs trust (SNT) becomes an indispensable tool. Understanding special needs trust basics for protecting a beneficiary is the first step toward creating a plan that offers both financial security and peace of mind.
A special needs trust is a legal arrangement that holds assets for the benefit of a person with a disability, known as the beneficiary, while preserving their eligibility for means-tested public benefits such as Supplemental Security Income (SSI) and Medicaid. Unlike a standard trust that might distribute funds directly to the beneficiary, an SNT is designed to supplement, not supplant, government benefits. The trustee uses trust assets to pay for things that improve the beneficiary's quality of life, like education, recreation, and personal care, without those funds counting as available resources. This article will walk you through the essential components of special needs trusts, from the different types available to the critical role of the trustee and the common pitfalls to avoid. For those ready to explore legal options, you can find lawyers in your city and request a quote through platforms like AttorneyDirectory.Lawyer, which connects individuals with legal professionals in various practice areas.
The Three Main Types of Special Needs Trusts
The type of special needs trust you choose depends on whose assets will fund the trust and what you hope to achieve. There are three primary categories: first-party trusts, third-party trusts, and pooled trusts. Each has distinct rules regarding funding, remainder beneficiaries, and how they interact with government benefits. Understanding these differences is fundamental to special needs trust basics for protecting a beneficiary.
A first-party special needs trust, also known as a self-settled trust, is funded with assets that belong to the beneficiary themselves. This often occurs when a person with a disability receives a personal injury settlement, an inheritance, or back payments from Social Security. Because the money is technically the beneficiary's, the government requires that any remaining funds in the trust be used to reimburse Medicaid for benefits paid during the beneficiary's lifetime. This type of trust must be established before the beneficiary turns 65 and is irrevocable. It is a powerful tool for preserving eligibility, but the Medicaid payback provision is a significant consideration.
A third-party special needs trust is funded with assets that belong to someone other than the beneficiary, such as a parent, grandparent, or other loved one. This is the most common type of SNT used in estate planning. Because the funds never belonged to the beneficiary, there is no Medicaid payback requirement. The person creating the trust can name remainder beneficiaries, such as siblings or charities, who will receive any remaining assets after the beneficiary's death. This flexibility makes third-party trusts an attractive option for parents who want to provide for a child with special needs without disinheriting other family members.
A pooled special needs trust is managed by a nonprofit organization and combines assets from multiple beneficiaries for investment purposes. Each beneficiary has their own sub-account, but the funds are pooled for administrative efficiency. Pooled trusts are often used when the amount of money is too small to justify the cost of a standalone trust, or when there is no family member available to serve as trustee. They are also subject to Medicaid payback rules if funded with the beneficiary's own assets. Many nonprofit organizations offer pooled trusts as a cost-effective alternative, though families should carefully review the fees and investment options.
How Trust Distributions Affect SSI and Medicaid Eligibility
The core purpose of a special needs trust is to protect the beneficiary's eligibility for SSI and Medicaid. SSI provides a monthly cash benefit to people with limited income and resources, while Medicaid covers healthcare costs. Both programs have strict limits on the assets and income a person can have. In most states, an SSI recipient cannot have more than $2,000 in countable resources. If a beneficiary receives a large sum of money directly, they could lose eligibility until those funds are spent down. An SNT solves this problem by holding the assets outside of the beneficiary's name, so they are not counted as a resource.
However, not all distributions from a trust are treated equally. The trustee must understand which types of payments are permissible and which could trigger a reduction or loss of benefits. In general, distributions that pay for food, shelter, or cash given directly to the beneficiary can be counted as in-kind income and reduce the SSI benefit. For example, if the trust pays the beneficiary's rent, that payment may be considered income and could lower the SSI check by up to one-third. On the other hand, distributions for items like a new computer, a vacation, or medical equipment not covered by Medicaid are typically allowed and do not affect benefits. The trustee must use discretion and follow detailed spending guidelines to avoid unintended consequences.
Medicaid eligibility is also a concern. While Medicaid rules vary by state, the trust must be structured to avoid being considered an available resource. For first-party trusts, the Medicaid payback provision is a federal requirement. For third-party trusts, the trust is not subject to payback, but the trustee must still ensure that distributions do not inadvertently create a resource that counts against the beneficiary. Working with an experienced estate planning attorney is essential to draft a trust that clearly defines permissible distributions and gives the trustee the guidance needed to comply with complex benefit rules.
Naming a Trustee and Drafting Spending Guidelines
The trustee is the person or institution responsible for managing the trust assets and making distributions on behalf of the beneficiary. Choosing the right trustee is one of the most critical decisions in the special needs trust basics for protecting a beneficiary. The trustee must be financially savvy, trustworthy, and knowledgeable about government benefits. They also need to be compassionate and understand the beneficiary's unique needs and preferences. A family member, such as a sibling or close friend, is often chosen, but professional trustees, such as banks or trust companies, can also serve. Each option has trade-offs: family members may be more attuned to the beneficiary's personal situation but may lack expertise, while professional trustees offer expertise but charge fees and may be less flexible.
Regardless of who serves as trustee, the trust document should include clear spending guidelines. These guidelines help the trustee understand what the grantor intended and provide a defense against accusations of mismanagement. A well-drafted trust might list examples of permissible distributions, such as:
- Educational expenses, including tuition, books, and tutoring
- Recreational activities, such as vacations, hobbies, and entertainment
- Medical and dental expenses not covered by insurance or Medicaid
- Personal care items, clothing, and electronics
- Transportation costs, including vehicle maintenance or public transit passes
It is equally important to specify what the trust should not pay for, such as rent, mortgage, or cash gifts that could reduce benefits. The trustee should also have the authority to make discretionary decisions, meaning they can choose whether and when to make a distribution based on the beneficiary's needs and the trust's resources. This flexibility is crucial because the beneficiary's circumstances may change over time.
In addition to spending guidelines, the trust should address how the trustee will be compensated, whether they can hire professionals, and how they should report to the beneficiary or other interested parties. A successor trustee should also be named to ensure continuity if the original trustee can no longer serve. Regular communication and transparency between the trustee and the family can help prevent disputes and ensure the trust is administered according to the grantor's wishes.
Common Funding Mistakes and How to Avoid Them
Even with the best intentions, families often make mistakes when funding a special needs trust. One of the most common errors is failing to actually fund the trust. A trust is only effective if assets are transferred into it. This might mean retitling bank accounts, changing beneficiary designations on life insurance policies, or transferring real estate. If a trust is mentioned in a will but never funded, the assets will pass through probate and may not be available to the beneficiary in the way intended. Working with an attorney to ensure proper funding is essential.
Another frequent mistake is commingling assets. The trustee must keep trust assets separate from their own personal funds and from the beneficiary's other assets. This means opening a separate bank account in the name of the trust and maintaining meticulous records. Commingling can lead to legal complications, tax issues, and potential loss of benefits. Trustees should also avoid making distributions directly to the beneficiary when a direct payment to a third party would be more appropriate. For example, paying a landlord directly for rent is generally preferable to giving the beneficiary cash to pay rent, as cash can be counted as income.
Families also sometimes overlook the importance of coordinating the special needs trust with their overall estate plan. This includes updating beneficiary designations on retirement accounts and life insurance policies, as well as ensuring that other family members understand the trust's purpose. A common pitfall is leaving assets outright to a sibling with the informal instruction to care for the beneficiary. This approach is risky because the sibling's own creditors could attach the funds, or the sibling might not follow through. Instead, the sibling's inheritance can be directed into a third-party special needs trust for the beneficiary's benefit. For business owners, it is also wise to consider how business succession plans interact with estate planning; resources like intellectual property basics for startups can provide useful context on protecting business assets, though the focus here remains on personal estate planning.
Finally, failing to review and update the trust is a mistake that can have long-term consequences. Life circumstances change: the beneficiary's needs may evolve, tax laws may change, and the trustee may need to be replaced. A periodic review every three to five years, or after major life events, can help ensure the trust remains effective and aligned with the grantor's goals.
Coordinating the Trust with Your Will and Estate Plan
A special needs trust should never exist in isolation. It must be integrated into a comprehensive estate plan that includes a will, powers of attorney, and possibly other trusts. For parents of a child with special needs, the estate plan often centers on ensuring that the child is cared for after the parents' death. This means creating a third-party special needs trust and funding it with life insurance or other assets. The will can direct that any assets passing to the child be directed into the trust rather than distributed outright. This coordination prevents the child from receiving a direct inheritance that could disqualify them from benefits.
It is also important to consider who will serve as the beneficiary's advocate and caregiver after the parents are gone. A special needs trust can provide financial resources, but it cannot replace the personal care and oversight that a family member provides. Some estate plans include a letter of intent that outlines the beneficiary's daily routine, medical needs, and preferences, which can guide future caregivers and trustees. Nominating a guardian for a minor child or a caregiver for an adult with disabilities is another critical component. The guardian and trustee roles are distinct and should ideally be filled by different people to provide checks and balances.
For those who need assistance with estate planning or special needs trusts, finding a qualified attorney is essential. The Lawyer Directory is not a law firm or a lawyer referral service, but it can help you connect with attorneys in your area who practice in estates and trusts. You can request a quote from participating attorneys with no obligation to hire. This can be a valuable first step in understanding your options and getting personalized advice. When you are ready to begin, consider reaching out to legal professionals who can guide you through the complexities of special needs trust basics for protecting a beneficiary.
Ultimately, a special needs trust is more than a legal document; it is a statement of love and foresight. It allows you to provide for a loved one with a disability in a way that respects their dignity and independence while safeguarding the benefits that are vital to their well-being. By understanding the basics, avoiding common mistakes, and working with knowledgeable professionals, you can create a plan that offers lasting security and peace of mind for your entire family.