
Medical Debt Relief Legal Options for Hospital Bills
Explore medical debt relief legal options for managing hospital bills, from negotiation to bankruptcy. Call (833)-248-4565 for professional guidance.
By Aaron Owens
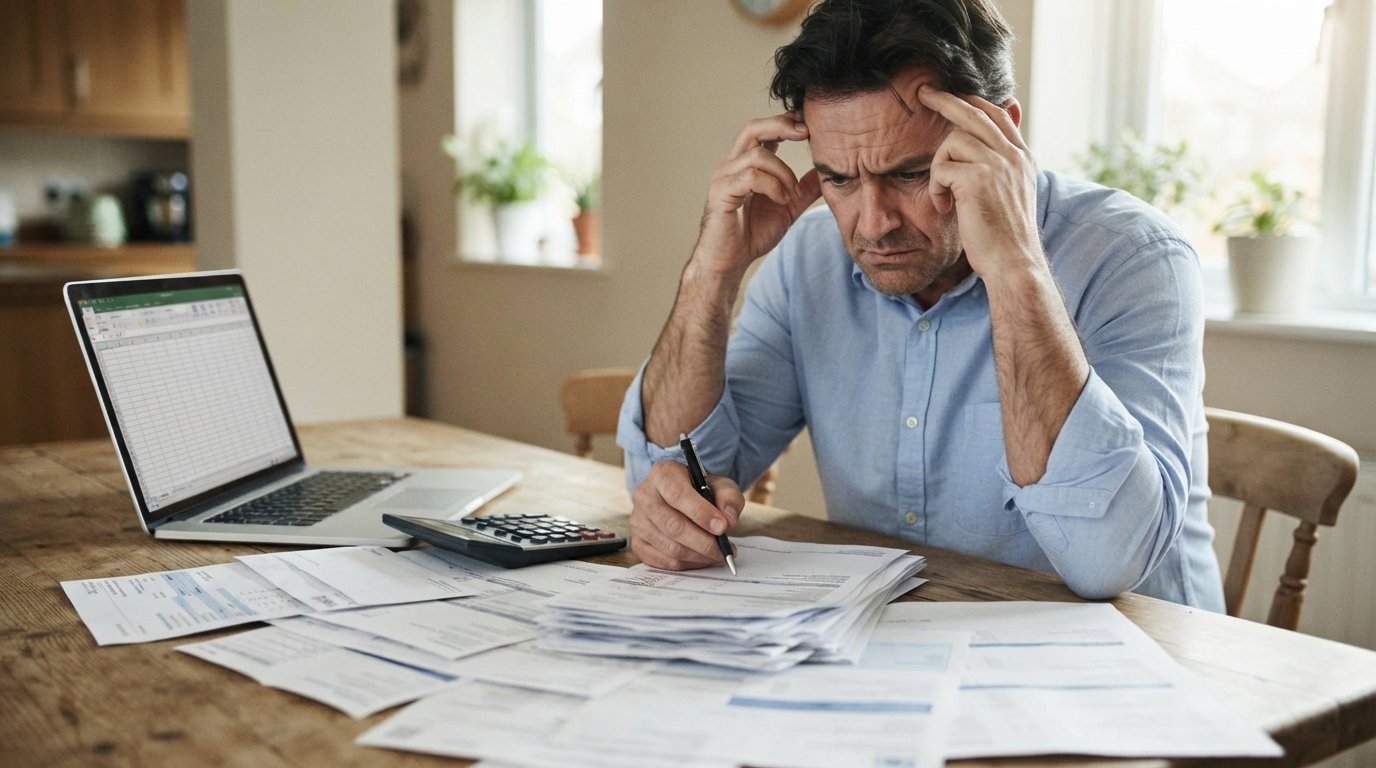
Hospital bills can arrive like a financial shock, even when you have insurance. A single emergency room visit, an out-of-network specialist, or a lengthy inpatient stay can generate charges that dwarf your monthly income. If you are staring at a stack of statements and wondering how you will ever pay them, you are not alone. Medical debt is a leading cause of financial distress in the United States, but it is also a problem with more solutions than many people realize. The key is understanding your rights, the legal tools available, and how to navigate the system without panicking.
This guide explores medical debt relief legal options for managing hospital bills. It covers practical steps like reviewing bills for errors and negotiating directly with providers, consumer protections that limit how medical debt appears on your credit report, and formal legal strategies such as debt settlement and bankruptcy. You will also learn how the two main bankruptcy chapters treat medical debt differently and when it makes sense to consult a debt relief attorney. Throughout, keep in mind that this information is educational, not legal advice. For guidance on your specific situation, consider requesting a quote from a qualified attorney in your area.
Start by Scrutinizing Every Bill and Statement
Before you consider any formal legal option, take a hard look at the bills themselves. Billing errors in healthcare are surprisingly common. Duplicate charges, incorrect procedure codes, services you never received, and balance billing after insurance adjustments can all inflate what you owe. Request an itemized statement from the hospital, not just a summary bill. Compare it against your insurance explanation of benefits (EOB) to spot discrepancies. If something does not add up, call the hospital's billing department and ask for a detailed review. Many providers will correct errors promptly once you point them out.
Once you have a verified bill, you can begin negotiating. Hospitals often have financial assistance programs, sometimes called charity care, that can reduce or eliminate your balance based on income. Ask about these programs explicitly. You can also propose a payment plan or a lump-sum settlement for less than the full amount. Negotiation is not a legal proceeding, but it is a powerful tool. If you feel overwhelmed, a patient advocate or a consumer law attorney can help you communicate with the hospital and insurers.
Know Your Consumer Protections for Medical Debt
Federal and state laws offer important safeguards. Recent changes by the major credit bureaus have removed many medical debts from credit reports, and the Consumer Financial Protection Bureau (CFPB) has taken steps to curtail abusive collection practices. For example, medical debt under $500 is no longer reported by the three largest credit bureaus, and paid medical collections are removed. These protections do not erase the debt, but they reduce the immediate damage to your credit score and give you breathing room to negotiate.
Additionally, the No Surprises Act protects patients from unexpected out-of-network bills in emergency situations and for certain scheduled services. If you receive a surprise bill that violates these rules, you can dispute it. Understanding these protections is a form of legal self-defense. If a collector harasses you or misrepresents the debt, you may have grounds for a claim under the Fair Debt Collection Practices Act (FDCPA). An attorney can advise you on whether your rights have been violated.
Debt Settlement and Negotiation: A Middle Path
Debt settlement involves negotiating with a creditor or collector to accept a lump sum that is less than the full balance. This can be done on your own or through a debt settlement company, though you should be cautious about fees and promises. For medical debt, hospitals and collection agencies may be willing to settle because they know that collecting from an individual can be costly and uncertain. A typical settlement might range from 30 to 60 percent of the original balance, depending on the age of the debt and your ability to pay.
However, debt settlement is not without risks. It may have tax consequences (forgiven debt can count as taxable income), and it can damage your credit if accounts go delinquent before settlement. That is why consulting an attorney before entering a settlement agreement is wise. An attorney can review the terms, ensure the agreement releases you from further liability, and help you avoid scams. If you are considering this route, start by gathering all your bills and any collection letters, then seek a professional evaluation.
How Bankruptcy Treats Medical Debt
Bankruptcy is a federal legal process that can discharge many types of unsecured debt, including medical bills. It is often viewed as a last resort, but for some people it provides the cleanest path to financial recovery. The two main chapters for individuals are Chapter 7 and Chapter 13. Each handles medical debt differently, and understanding the distinctions is crucial.
Chapter 7 Bankruptcy: Liquidation and Discharge
Chapter 7 is known as liquidation bankruptcy. It involves selling nonexempt assets to pay creditors, but many filers have few assets and can keep essential property under state exemptions. Medical debt is treated as a general unsecured claim, meaning it is low priority and often discharged entirely if you qualify. To qualify for Chapter 7, you must pass a means test based on your income. If you earn below the median income in your state, you likely qualify. The entire process typically takes three to six months, and the discharge eliminates most medical debts. However, it can negatively affect your credit for several years, and some debts (like recent taxes or student loans) are not dischargeable.
Chapter 13 Bankruptcy: Reorganization and Repayment
Chapter 13 is a reorganization bankruptcy for individuals with regular income. Instead of liquidating assets, you propose a repayment plan to pay back some or all of your debts over three to five years. Medical debt is included in the plan as unsecured debt, and you may pay only a fraction of what you owe, with the remainder discharged at the end of the plan. Chapter 13 is often used by people who want to save their home from foreclosure or who earn too much to qualify for Chapter 7. It is more complex and requires steady income to make plan payments. The advantage is that it can provide immediate protection from collection actions while you catch up.
Choosing between Chapter 7 and Chapter 13 depends on your income, assets, and goals. A bankruptcy attorney can help you determine which chapter fits your situation and whether bankruptcy is the right choice at all. Keep in mind that bankruptcy is a serious step with long-lasting effects, but for some, it is the only way to eliminate overwhelming medical debt.
When to Consult a Debt Relief Attorney
If you have tried negotiating, reviewed your bills, and still feel buried, it may be time to speak with an attorney. Legal professionals who focus on debt relief, consumer law, or bankruptcy can evaluate your options and help you avoid costly mistakes. They can also deal with aggressive collectors and ensure your rights are protected. Many offer free or low-cost initial consultations.
To connect with an attorney, you can use a directory like AttorneyDirectory.Lawyer to find lawyers in your city and request a quote. The platform is not a law firm or a referral service, but it allows you to describe your legal concern and location, and participating attorneys may contact you with information about their services. There is no obligation to hire, so you can explore your options without pressure. Similarly, if you are dealing with other legal issues like an HOA dispute, you might find our guide on HOA dispute resolution legal options for homeowners helpful for understanding how to navigate those challenges.
When you meet with an attorney, bring all your medical bills, insurance statements, collection letters, and a summary of your income and expenses. Be honest about your financial situation so they can provide accurate advice. Ask about fees upfront and understand what services are included. Whether you choose negotiation, settlement, or bankruptcy, having a knowledgeable advocate on your side can make a difficult process more manageable.
Medical debt can feel like a trap, but it does not have to define your financial future. By taking proactive steps, understanding your legal rights, and seeking professional guidance when needed, you can find a path forward. Start by reviewing your bills, exploring assistance programs, and learning about the legal options available. Help is available if you know where to look.