
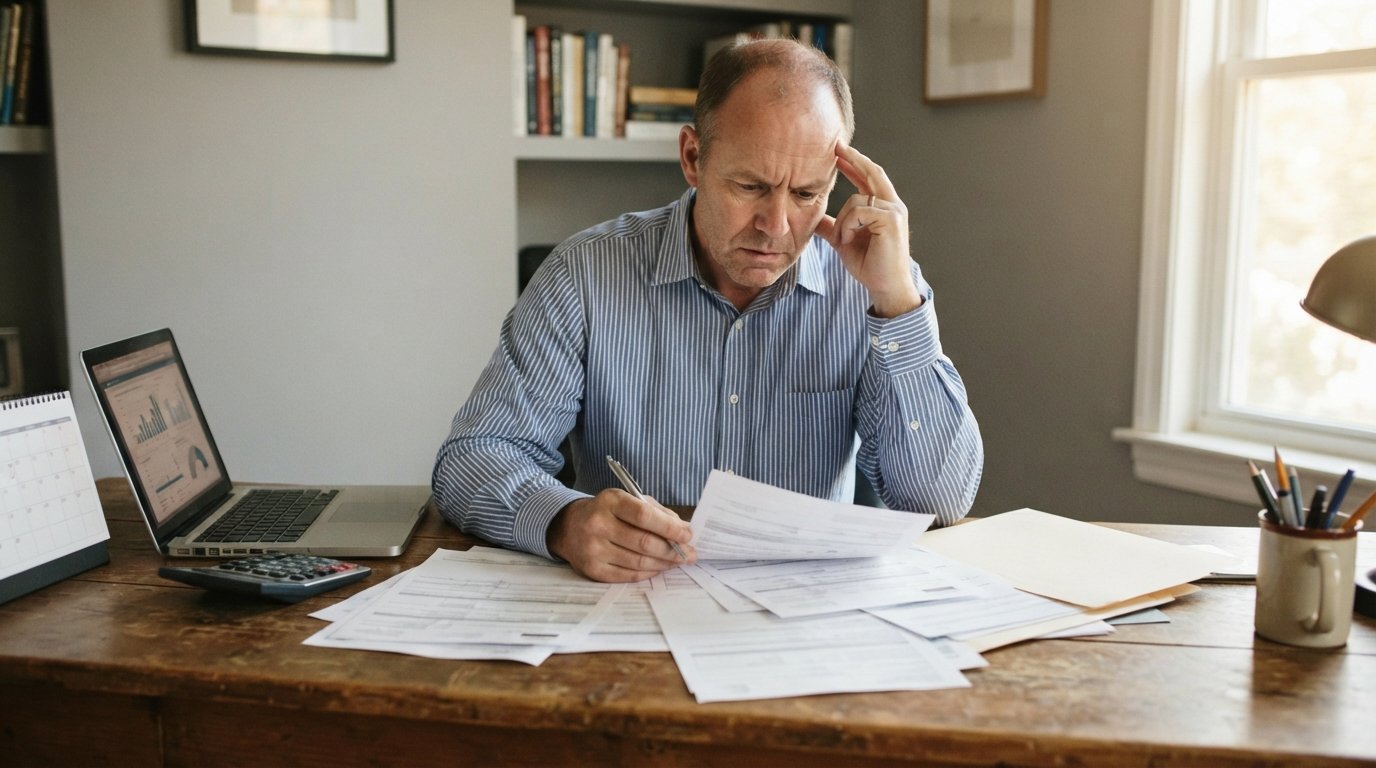
How to Appeal a Long Term Disability Insurance Denial
Facing a long term disability denial? Learn how to appeal with stronger evidence and meet deadlines. Call (833)-248-4565 for guidance.
By Luis Navarro
Your long term disability insurer just sent a denial letter, and the clock is already ticking. Whether the denial cites insufficient medical evidence, a pre-existing condition, or a dispute over whether you meet the policy's definition of disability, you have the right to fight back. The appeal process is technical, deadline-driven, and stacked in the insurer's favor, but policyholders who understand the rules and build a well-documented case can and do win. This guide walks you through how to appeal a long term disability insurance denial step by step, from reading the denial letter to preparing for an external review.
Start by Decoding the Denial Letter and Your Policy
The denial letter is your roadmap. Insurers are required to explain the specific reasons for the denial, cite the policy provisions they relied on, and tell you how to appeal. Read it slowly and take notes. Common reasons include a conclusion that your medical records do not support functional limitations, a finding that your condition is excluded, a dispute about your occupation or earnings, or a claim that you missed a deadline or submitted incomplete paperwork.
Next, pull out your policy and locate the definition of disability. Most long term disability policies use one of two standards: "own occupation" (you cannot perform the duties of your specific job) or "any occupation" (you cannot perform any job for which you are reasonably suited by education, training, or experience). Many policies switch from own occupation to any occupation after 24 months, which is a frequent flashpoint in denials. Also check the elimination period, the maximum benefit period, and any offsets for Social Security or workers' compensation benefits.
Pay close attention to the appeal deadline. Under the Employee Retirement Income Security Act (ERISA), which governs most employer-provided disability plans, you typically have at least 180 days from the denial to file an internal appeal. Individual policies regulated by state law may set shorter windows, sometimes 60 or 90 days. Missing the deadline can end your case before it begins, so mark the date on your calendar immediately and work backward from it.
Build a Complete Medical Record Before You Write a Word
Insurers deny claims when the file does not clearly connect your diagnosis to functional limitations. A diagnosis of chronic pain, fibromyalgia, or depression is not enough on its own; the insurer wants to see objective evidence that you cannot sit, stand, lift, concentrate, or perform your job duties reliably. Before drafting your appeal, request a complete copy of your claim file from the insurer, including the medical records they reviewed, the vocational analysis, and any internal reviewer notes. You are entitled to these documents under ERISA and most state insurance regulations.
Then assemble evidence that fills the gaps the insurer identified. Useful items often include:
- Treatment notes and test results from every provider, including specialists, physical therapists, and mental health professionals
- A detailed statement from your treating physician describing your functional limitations and why they prevent you from working
- Records of medications, side effects, and failed treatments that show the severity of your condition
- Third-party observations from family members or coworkers about how your condition affects daily life
- Vocational evidence, such as a job description and an analysis showing why your restrictions conflict with your duties
A common mistake is sending raw records without explanation. Insurers employ reviewers who spend minutes, not hours, on each file. A short cover letter that maps each limitation to a specific policy requirement and points the reviewer to the relevant page numbers makes it far harder to ignore your evidence. If your doctor is willing, ask for a letter that uses the policy's language directly, for example stating that you cannot perform the material duties of your own occupation on a full-time basis.
Keep in mind that the insurer may have surveillance or independent medical examination reports in the file. Review them carefully and rebut any inaccuracies with your own evidence. If a functional capacity evaluation or a specialist opinion would strengthen your case, discuss it with your doctor before the appeal deadline.
Follow the Internal Appeal Rules to the Letter
ERISA internal appeals have strict procedural requirements. Your appeal must generally be in writing, submitted within the deadline, and include the arguments and evidence you want the insurer to consider. Many plans allow only one mandatory internal appeal before you can go to court, so treat it as your best shot. Some plans permit a second voluntary appeal, but you should not count on it.
Structure your appeal as a formal submission. Begin with a summary of the denial and a clear statement that you are appealing. Then address each reason for denial in turn, citing the policy language and the evidence that contradicts the insurer's conclusion. Attach an index of exhibits so the reviewer can navigate the file. If the denial relied on a paper review by a physician who never examined you, point out the limitations of that review and contrast it with the opinions of treating providers who know your condition over time.
Timing matters on the insurer's side too. ERISA generally requires the plan to decide a disability appeal within 45 days after receiving it, with possible extensions of up to 45 more days for special circumstances. If the insurer misses those deadlines, you may have grounds to challenge the denial in court. Keep copies of everything you send, use a trackable delivery method, and confirm receipt.
If your policy is an individual policy rather than an employer plan, state law and the policy itself govern the process. Some states require insurers to accept new evidence at the appeal stage and to provide a reasonable opportunity to respond to any new information they rely on. Read your policy and any state insurance department guidance carefully, or consult an attorney if the rules are unclear.
When to Bring in a Disability Attorney
You are not required to hire a lawyer to appeal a long term disability denial, but the stakes are high and the insurer has a team of professionals working against you. Consider consulting an attorney before filing the internal appeal if your claim involves a large benefit amount, a disputed occupational definition, a mental health limitation, or a denial that seems to ignore your medical evidence. An attorney can help you obtain the claim file, identify the insurer's vulnerabilities, and draft an appeal that preserves your right to sue.
Timing is especially important because courts often defer to the insurer's decision if the administrative record was not fully developed during the internal appeal. In many ERISA cases, evidence not submitted before the appeal deadline cannot be used later in litigation. An attorney can help you build a complete record now rather than discovering too late that a key document was missing.
If you are also navigating public benefits, note that long term disability insurers often require you to apply for Social Security Disability Insurance (SSDI). A denial at the SSDI level does not automatically doom your private claim, but the two processes interact. For related guidance on public benefit planning, see our article on Medicaid planning for long-term care, which explains how benefit programs can affect long-term care planning.
Finding the right attorney does not have to be complicated. You can use a U.S. lawyer directory such as AttorneyDirectory.Lawyer to find disability and insurance attorneys in your city and request a quote. The directory is not a law firm or a lawyer referral service, and there is no obligation to hire, but it gives you a straightforward way to compare options and ask questions before committing.
Prepare for External Review and Possible Litigation
If the internal appeal is denied, you may have options outside the insurer. For ERISA plans, the next step is usually filing a lawsuit in federal court to challenge the denial. For individual policies, you may have the right to an external review by an independent review organization, depending on your state's insurance laws. External review typically involves submitting your records and arguments to a reviewer who is not employed by the insurer, and the reviewer's decision may be binding on the insurer.
Before an external appeal, make sure your file is as strong as possible. Update your medical records, obtain a fresh statement from your treating physician if your condition has changed, and prepare a concise summary of why the denial is wrong. Review any new evidence the insurer submits and respond to it within the deadlines. If you have not already consulted an attorney, this is often the point where legal help pays for itself, because the procedural rules become more complex and the deadlines tighter.
Throughout the process, keep a detailed log of every phone call, letter, and submission. Insurers sometimes make errors, miss deadlines, or rely on outdated records, and a clear paper trail can make the difference in an appeal or a lawsuit. Stay organized, stay within deadlines, and do not give up after the first denial. Many successful disability claims are won on appeal with better evidence and a sharper argument.
Appealing a long term disability denial is a project, not a single letter. Read the denial carefully, gather the records that prove your limitations, follow the plan's rules precisely, and get help when the stakes justify it. With a disciplined approach, you can force the insurer to take a second look and improve your chances of securing the benefits you paid for.