
Elder Law Legal Issues Affecting Older Adults
Navigate elder law legal issues affecting older adults with confidence. Call (833)-248-4565 to find local attorneys and request a no-obligation quote.
By Olivia Turner
As the population ages, more families are confronting legal questions they never expected to face. A parent's sudden illness, a suspicious call from someone claiming to be a grandchild, or the need to move a loved one into assisted living can quickly turn into a maze of legal and financial decisions. Elder law exists to help older adults and their families navigate these issues with clarity and protection. This article explains the most common elder law legal issues affecting older adults, from estate planning and powers of attorney to exploitation, long-term care, and guardianship, so you can recognize when to seek professional guidance.
Why Elder Law Deserves Attention Now
Elder law is not a single statute or a narrow practice area. It is a holistic approach to the legal needs of aging individuals, combining elements of estate planning, healthcare law, public benefits, and advocacy against abuse. The stakes are high: decisions made in a crisis often cost more and limit options. Planning ahead, even in a basic way, preserves autonomy and reduces family conflict.
One challenge is that many older adults do not realize how quickly capacity can change. A fall, a stroke, or an early dementia diagnosis can remove the ability to sign documents or make decisions. Without proper legal tools in place, families may need court intervention. Understanding the core issues helps you act before a crisis and ask the right questions when meeting with an attorney.
Estate Planning, Powers of Attorney, and Healthcare Directives
Estate planning is the foundation of elder law. For older adults, it goes beyond deciding who inherits the house. It includes documents that operate during life, not just after death. A will directs property after death, while trusts can manage assets, avoid probate, and provide for a surviving spouse or a child with special needs. But the most urgent documents for many seniors are those that authorize someone to act while they are still alive.
A durable power of attorney lets a trusted person handle financial matters, such as paying bills, managing bank accounts, or selling property. A healthcare power of attorney, sometimes paired with a living will, spells out medical wishes and names a decision maker if the patient cannot speak for themselves. These documents must be signed while the person has capacity, and they should be updated after major life changes like divorce or the death of a named agent.
Families often ask what happens if a parent refuses to sign anything. That is a common and difficult situation. An elder law attorney can explain options, including limited guardianship, but the best outcome is usually voluntary planning. If you are preparing to meet with a lawyer, it helps to understand the terminology first; our guide on common legal terms explained before meeting a lawyer can make the first conversation more productive.
To organize the planning process, consider these steps:
- Inventory assets, debts, and income sources, including Social Security, pensions, and retirement accounts.
- Decide who should serve as agent under financial and healthcare powers of attorney, and name backups.
- Review beneficiary designations on retirement accounts and life insurance, which override a will.
- Discuss long-term care wishes and whether a trust or other tool is appropriate for your situation.
- Store original documents in a safe, accessible place and tell your agent where they are.
Completing these steps does not require a large estate. Even modest assets can trigger probate delays or family disputes if no plan exists. An estate planning or elder law attorney in your city can tailor documents to your state's rules and your family's dynamics.
Protection From Elder Abuse, Neglect, and Financial Exploitation
Elder abuse takes many forms: physical harm, emotional manipulation, neglect by caregivers, and financial exploitation. Financial exploitation is especially common and often hidden. It can involve a stranger who convinces an older adult to wire money, a family member who pressures a relative to change a will, or a caregiver who uses a credit card without permission. Scams targeting seniors, such as fake tech support calls or romance fraud, cost billions each year.
Warning signs include sudden changes in bank accounts, unpaid bills despite adequate income, new friends who isolate the older adult from family, and documents that appear signed under unusual circumstances. If you suspect abuse, document what you observe and contact Adult Protective Services in your state. In emergencies, call 911. Legal remedies can include restraining orders, civil lawsuits to recover assets, and in some cases criminal prosecution.
Prevention matters as much as response. Simple safeguards help:
- Name a trusted agent under a power of attorney and require that person to keep records.
- Set up automatic alerts with banks and credit card companies for unusual transactions.
- Add a trusted contact to financial accounts so institutions can reach a family member if concerns arise.
- Review credit reports annually and consider a credit freeze if fraud is suspected.
- Educate older adults about common scams and encourage them to verify requests independently.
An elder law attorney can help families recover from exploitation, revise estate documents that were improperly changed, and coordinate with financial institutions. Because exploitation often involves family members, legal guidance can also help preserve relationships while protecting assets.
Medicare, Medicaid, and Long-Term Care Planning Basics
Healthcare costs are a central concern for older adults. Medicare provides federal health coverage for those 65 and older and some younger people with disabilities. It covers hospital stays, doctor visits, and prescription drugs, but it does not pay for most long-term custodial care, such as help with bathing, dressing, or eating in a nursing home or at home. That gap is where Medicaid and private planning come in.
Medicaid is a joint federal-state program that pays for long-term care for people with limited income and assets. The rules are complex and vary by state. There is a five-year look-back period for asset transfers, meaning gifts or transfers made within five years of applying can cause a penalty period of ineligibility. Many families mistakenly transfer assets to children without understanding the consequences. Proper planning can preserve eligibility while allowing a spouse to keep certain resources.
Long-term care planning may involve irrevocable trusts, caregiver agreements, or conversions of assets. It is not about hiding money; it is about using the rules lawfully to avoid impoverishment. An elder law attorney can review your finances and explain options such as Medicaid planning, veterans benefits, and home care arrangements. If you need to find a lawyer who focuses on these issues, you can search a trusted attorney directory by location and practice area, then request a quote with no obligation to hire.
Timing is critical. Planning before a health crisis gives you more choices. Once a person enters a nursing home or needs immediate care, options narrow. Families should start conversations about long-term care early, even if the need seems years away.
Guardianship and Conservatorship When Capacity Declines
When an older adult can no longer make safe decisions about finances or healthcare, and no valid power of attorney exists, a court may appoint a guardian or conservator. Guardianship typically covers personal decisions like housing and medical care, while conservatorship covers financial matters. The terminology varies by state, and a court supervises the arrangement.
Guardianship is sometimes necessary, but it is restrictive. The person under guardianship may lose the right to vote, marry, or make contracts. Courts prefer the least restrictive alternative, such as a limited guardianship or a supported decision-making agreement. Families should consider whether a power of attorney, a revocable trust, or a healthcare proxy could avoid court involvement. If guardianship is unavoidable, the process requires medical evidence, notice to family members, and a hearing.
A common scenario involves an adult child who notices a parent forgetting to pay bills or wandering outside. Before rushing to court, consult an elder law attorney. Sometimes a durable power of attorney signed years earlier is still valid, or a family member can help with informal supports. When capacity is genuinely gone, an attorney can guide the petition and help select a responsible guardian.
Finding an Elder Law or Estate Attorney in Your City
Elder law issues often overlap with estate planning, but not every estate attorney handles Medicaid planning or exploitation cases. Look for a lawyer who practices elder law specifically, or one who combines estate planning with public benefits and advocacy. State-specific knowledge matters because Medicaid rules, guardianship procedures, and document requirements differ across the country.
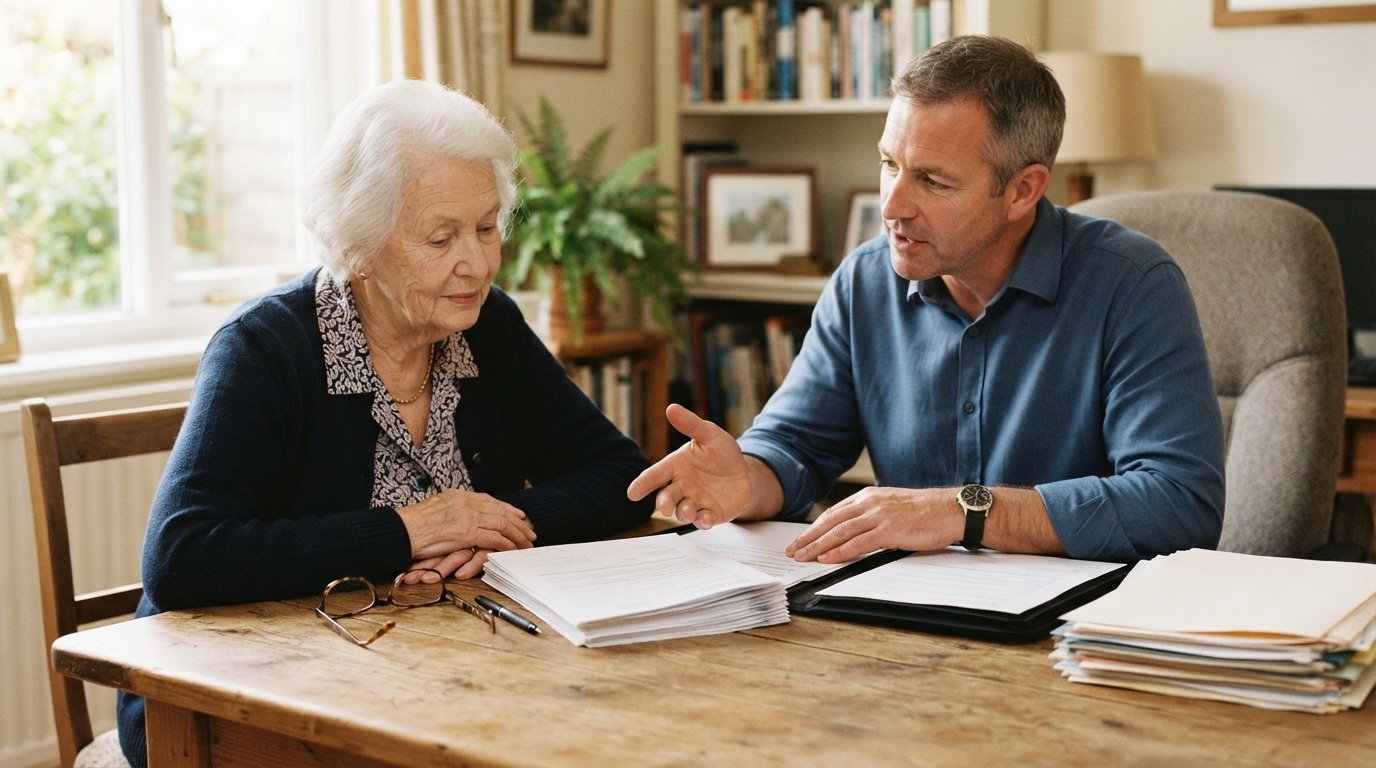
Start by gathering key documents: existing wills, trusts, powers of attorney, healthcare directives, recent financial statements, and a list of medications and doctors. Write down your questions. At the initial consultation, ask about the attorney's experience with Medicaid planning, guardianship, and elder abuse. Ask how fees are structured and who will handle your case. A good attorney will explain options clearly and never pressure you into a decision.
If you are ready to connect with a local lawyer, you can use a directory to find attorneys in your city and request a quote. The process is informational and does not create an attorney-client relationship with the directory itself. Participating attorneys may contact you, and you decide whether to hire. For families facing elder law legal issues affecting older adults, that first conversation can turn confusion into a practical plan.