
Can Student Loans Be Discharged in Bankruptcy?
Student loans can be discharged in bankruptcy, but only with proof of undue hardship. Call (833)-248-4565 to explore your legal options today.
By Luis Navarro
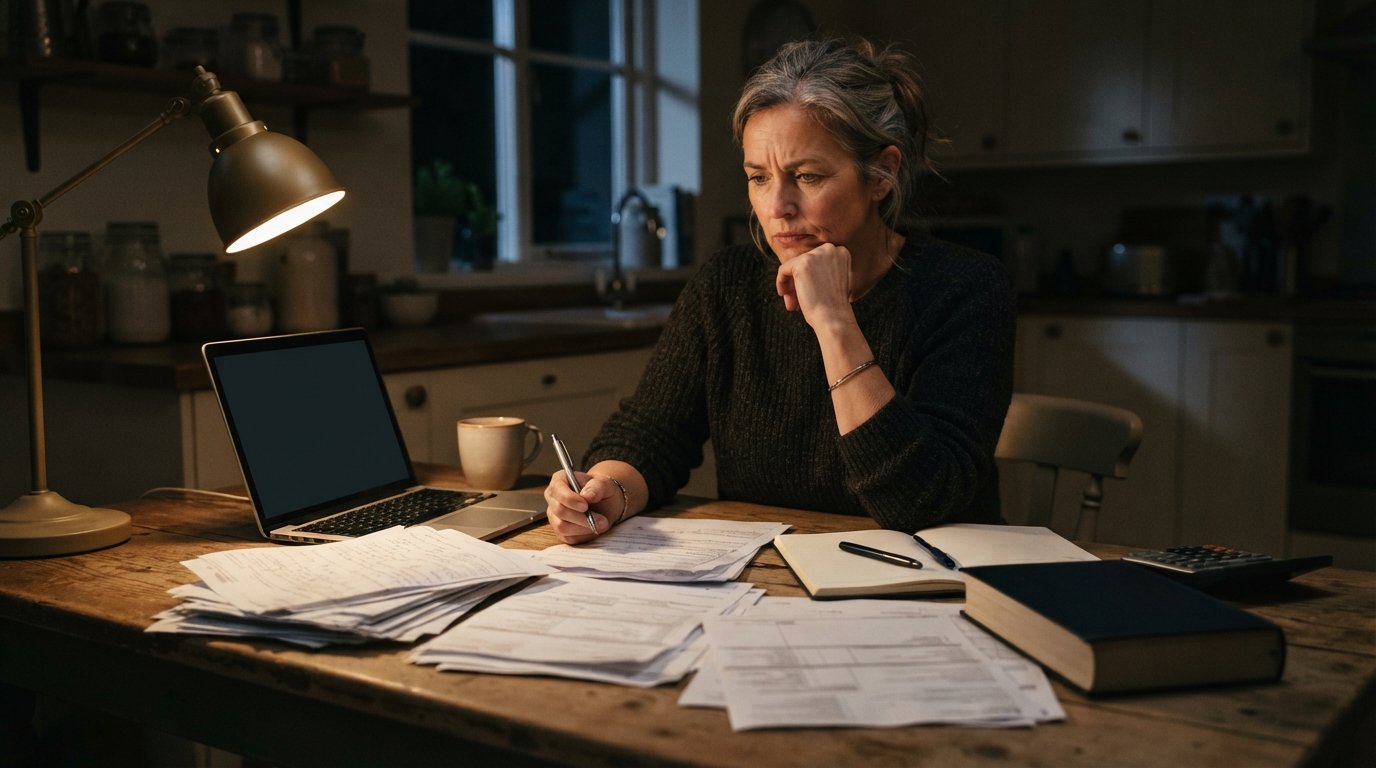
Roughly 43 million Americans carry federal student loan debt, and millions more owe private education loans. When payments become unmanageable, bankruptcy often enters the conversation, usually followed by the same discouraging refrain: student loans cannot be discharged. That blanket statement is misleading. Federal student loans can be discharged in bankruptcy, but only when the borrower proves "undue hardship" in a separate court proceeding. The path is narrow, evidence-heavy, and rarely self-guided, yet it exists, and a growing number of borrowers walk it successfully every year. Understanding the legal standard, the procedural steps, and the alternatives can help you decide whether bankruptcy is a realistic option or whether a different relief strategy fits your situation better.
Why Student Loans Are Treated Differently in Bankruptcy
Most consumer debts, including credit cards, medical bills, and personal loans, are wiped out in a Chapter 7 bankruptcy or restructured in a Chapter 13 repayment plan. Student loans occupy a special category. Under federal law, education loans are presumptively nondischargeable unless the borrower affirmatively proves undue hardship. This presumption applies to loans made or guaranteed by the government, most private student loans, and certain other educational obligations.
The policy rationale dates back decades: Congress worried that borrowers would rack up education debt and immediately erase it, leaving taxpayers to absorb the cost. Over time, that protection hardened into a near-myth that student loans are impossible to discharge. Courts, however, have always left the door open. The real question is not whether discharge is legally possible, but whether a particular borrower can meet the standard with credible evidence.
Two procedural facts matter from the start. First, simply listing a student loan on your bankruptcy schedules does not discharge it. Second, the burden rests entirely on the borrower. The lender is not required to prove anything. If you never file the extra paperwork, the loan survives bankruptcy automatically, even if you never hear a word from the servicer during the case.
What Undue Hardship Actually Means
Bankruptcy courts apply different tests depending on the federal circuit, but nearly all of them revolve around the same core idea: the borrower cannot maintain a minimal standard of living while repaying the loan, and that inability is likely to persist for a substantial portion of the repayment period. The most widely used framework is the Brunner test, named after a 1987 Second Circuit decision. A smaller number of circuits use the totality of the circumstances test, which weighs a broader set of factors.
Under the Brunner test, a borrower must prove three elements by a preponderance of the evidence. Courts examine each element separately, and failing any one of them usually defeats the discharge request:
- Poverty: Based on current income and expenses, the borrower cannot maintain a minimal standard of living while repaying the loan.
- Persistence: Additional circumstances indicate the hardship will continue for a significant part of the repayment period, such as disability, chronic illness, or long-term unemployment.
- Good faith: The borrower made genuine efforts to repay the loan or negotiate a workable arrangement before seeking discharge.
The totality of the circumstances test is more flexible. Courts weigh income, expenses, health, dependents, employment prospects, and good faith efforts together rather than as rigid gates. Some judges treat this approach as more borrower-friendly, but outcomes still depend heavily on documentation. In either framework, vague claims of financial strain are not enough. Judges want bank statements, tax returns, medical records, and evidence of payment attempts.
A common misconception is that unemployment alone proves hardship. Courts frequently reject that argument when the borrower has earning capacity, no dependents, or only temporary setbacks. Conversely, a borrower with a modest income but severe medical limitations and a long history of good-faith payments may prevail. The analysis is fact-specific, which is why the outcome varies so much from case to case.
The Adversary Proceeding: A Lawsuit Inside Your Bankruptcy
Seeking discharge of student loans requires filing an adversary proceeding, which is a separate lawsuit filed within the bankruptcy case. The borrower is the plaintiff, and the lender or loan servicer is the defendant. This is not a motion or a form attached to the bankruptcy petition. It is a formal complaint that initiates litigation, complete with summons, deadlines, discovery, and potentially a trial.
The process generally unfolds in a predictable sequence. After the bankruptcy case is filed, the borrower's attorney prepares and files a complaint to determine dischargeability. The lender responds, and both sides exchange documents and conduct discovery. Many cases settle through a stipulated judgment that discharges a portion of the debt or provides for a manageable payment plan. Others proceed to trial, where the judge issues a ruling that can discharge the loans entirely, partially, or not at all.
Timing matters. The adversary proceeding must be filed within the bankruptcy case, and courts enforce deadlines strictly. Filing late can forfeit the discharge opportunity entirely. There are also filing fees and potential litigation costs. For borrowers with substantial loan balances, the investment often makes sense; for someone owing a few thousand dollars, the cost may exceed the benefit. A bankruptcy attorney can evaluate whether the numbers justify the fight.
One practical development deserves attention: the Department of Justice and Department of Education have streamlined the process for federal loans in recent years, making it easier for borrowers to present hardship evidence and reach stipulated agreements. That does not mean discharge is automatic. It means the pathway is more navigable than it was a decade ago, and borrowers who might have been discouraged by the old process should reassess their options.
Chapter 7 Versus Chapter 13: Different Arenas for the Same Fight
Student loan discharge can be pursued in either Chapter 7 or Chapter 13 bankruptcy, but the mechanics differ. In Chapter 7, most unsecured debts are wiped out quickly, and the adversary proceeding runs alongside the case. In Chapter 13, the borrower proposes a three-to-five-year repayment plan, and student loans are typically treated as general unsecured claims unless the borrower takes additional steps to prioritize them.
Chapter 13 offers a distinctive advantage: the automatic stay temporarily halts collection activity, including wage garnishment and tax refund offsets, giving the borrower breathing room. Some courts also allow a partial discharge of student loans through a Chapter 13 plan, reducing the balance to a manageable amount rather than eliminating it entirely. The tradeoff is that the case lasts longer and requires consistent plan payments.
Choosing between chapters depends on income, assets, and the size of the loan balance. A borrower with steady income above the means-test threshold may not qualify for Chapter 7 at all. A borrower with significant equity in a home may prefer Chapter 13 to protect that asset. These calculations are precisely where professional guidance pays off, because the wrong chapter can waste time and money.
Alternatives Worth Exhausting Before Bankruptcy
Bankruptcy is not the only route to relief, and courts expect borrowers to explore other options first. That expectation is built into the good-faith prong of the Brunner test. Documenting your efforts with income-driven repayment plans, hardship forbearances, and settlement negotiations strengthens a later discharge case and may resolve the problem without litigation.
For federal loans, income-driven repayment plans cap monthly payments at a percentage of discretionary income and forgive remaining balances after 20 or 25 years of qualifying payments. Public Service Loan Forgiveness wipes out the balance after 10 years of payments for borrowers in qualifying government or nonprofit jobs. Total and Permanent Disability discharge is available for borrowers who cannot work due to disabling conditions. Teacher Loan Forgiveness and various borrower defense claims address specific circumstances.
Private student loans lack these federal safety nets, but lenders sometimes offer hardship programs, interest rate reductions, or settlement agreements. Refinancing can lower payments, though it rarely solves an underlying affordability problem. A guide on student loan debt relief options beyond bankruptcy can help borrowers map the alternatives before committing to a bankruptcy filing.
There is a strategic reason to document every alternative you try. If you later file an adversary proceeding, the lender will argue you did not act in good faith. A file showing years of payment attempts, hardship applications, and communication with servicers rebuts that argument effectively. Borrowers who ignore their loans for years and then seek discharge face an uphill battle.
How an Attorney Prepares a Hardship Case
Winning a student loan discharge is largely an exercise in evidence management. An experienced bankruptcy attorney builds a record that addresses each element of the applicable test, anticipates lender objections, and presents the borrower's circumstances in a credible, consistent way. The preparation typically involves several concrete steps:
- Gather financial documentation, including tax returns, pay stubs, bank statements, and a detailed monthly budget showing necessary expenses.
- Compile medical records, disability determinations, or employment records that support a long-term hardship claim.
- Reconstruct the payment history, including applications for income-driven repayment, forbearances, and any correspondence with servicers.
- Draft the adversary complaint with factual allegations tied directly to the legal standard in that circuit.
- Prepare the borrower for discovery and testimony, since credibility often decides close cases.
Attorneys also evaluate settlement leverage. Lenders know litigation is expensive and uncertain, so they sometimes agree to discharge a percentage of the balance or to a structured payment arrangement. A well-documented hardship case increases the odds of a favorable stipulation without a trial. Conversely, a thin complaint invites a motion to dismiss.
Borrowers should ask prospective attorneys about their experience with adversary proceedings specifically, not just consumer bankruptcy generally. Student loan litigation is a niche practice with its own procedural quirks and local court expectations. If you are unsure where to start, you can find lawyers in your city through AttorneyDirectory.Lawyer and request a consultation to discuss your situation.
State Variation and Local Court Practices
Bankruptcy law is federal, but local practices vary meaningfully. Some bankruptcy courts have adopted local rules or standing orders that shape how adversary proceedings proceed, including mediation requirements and scheduling timelines. Judges also differ in how strictly they apply the Brunner factors, particularly the persistence prong, which some courts interpret narrowly and others more generously.
Geography can also affect access to experienced counsel. Borrowers in rural areas may find fewer attorneys who handle student loan discharge cases, while urban areas typically offer more options. Because student loan litigation is specialized, distance learning or virtual consultations have become common, allowing borrowers to work with counsel outside their immediate area when local expertise is limited.
State law plays a secondary role in areas like property exemptions, which affect what assets are protected in bankruptcy, and in the treatment of certain private loans. These details rarely change the core undue hardship analysis, but they can influence strategy, especially in Chapter 13 cases where plan terms interact with state exemption rules.
Practical Steps to Take Now
If you are considering bankruptcy as a path to student loan relief, begin with a clear-eyed assessment of your finances. Pull your credit report, list every education loan with its balance and servicer, and calculate your actual monthly obligations. Compare that to your income and necessary expenses. This snapshot tells you whether hardship is arguable and which chapter might fit.
Next, contact your loan servicers and ask about income-driven repayment, forbearance, and any hardship programs. Keep records of every call, application, and response. Even if you ultimately pursue bankruptcy, this history supports the good-faith element of your case. If you have private loans, ask about settlement options and get any offers in writing.
Finally, consult a bankruptcy attorney who handles student loan discharge. Many offer initial consultations at little or no cost, and you can request a quote through a directory to compare options without obligation. Bring your loan documents, recent tax returns, and a summary of your financial situation. A candid conversation about the strengths and weaknesses of your hardship claim will save months of uncertainty and help you choose between bankruptcy, an administrative relief program, or a negotiated resolution.
Student loan discharge in bankruptcy is neither automatic nor impossible. It is a legal remedy with a demanding standard, a formal procedure, and a real track record of success for borrowers who prepare thoroughly. Whether it is the right remedy for you depends on facts that a qualified attorney can evaluate with you, and the earlier you start gathering those facts, the more options remain open.